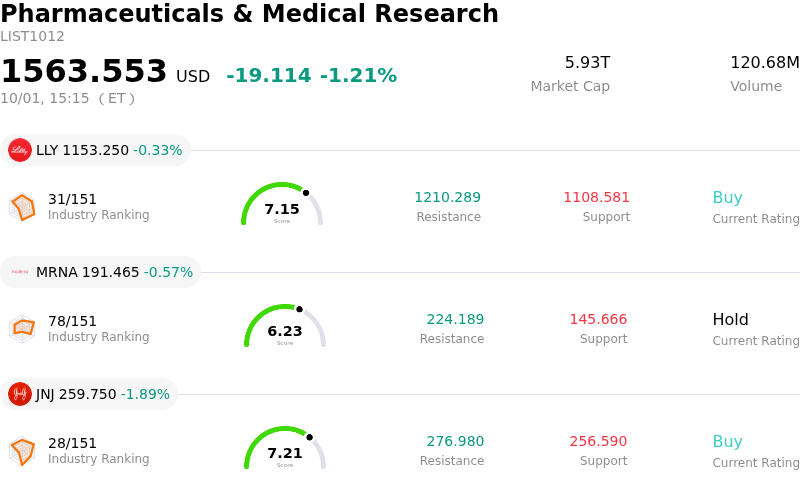
Vertex Pharmaceuticals Inc (VRTX) moved down by 3.21%. The Pharmaceuticals & Medical Research sector is down by 1.21%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) down 0.33%; Moderna Inc (MRNA) down 0.57%; Johnson & Johnson (JNJ) down 1.89%.
What is driving Vertex Pharmaceuticals Inc (VRTX)’s stock price down today?
Vertex Pharmaceuticals experienced downward pressure and heightened intraday volatility as broader macroeconomic headwinds, particularly elevated treasury yields, continued to weigh on high-valuation biotechnology equities. Institutional investors often recalibrate exposure to premium-priced growth names when discount rates remain elevated, creating short-term liquidity swings across large-cap healthcare stocks. Given that Vertex trades at a valuation premium relative to broader biopharmaceutical industry averages, market-wide volatility exerted additional pressure on the stock during the session.
Market sentiment was also influenced by ongoing investor evaluation of the company's capital allocation and expansion trajectory. Following the recent completion of its multi-billion-dollar acquisition of Crinetics Pharmaceuticals—designed to broaden Vertex's reach into specialty endocrinology with assets like Palsonify—investors are weighing long-term diversification benefits against short-term integration execution. The transaction, funded through a combination of existing cash reserves and debt, has drawn increased focus toward capital deployment efficiency and operating margin performance.
Furthermore, Wall Street analysts are closely tracking commercialization progress and profitability timelines across non-cystic fibrosis therapeutic lines. While Vertex continues to generate robust cash flows from its market-leading cystic fibrosis franchise, core market saturation requires seamless execution across expanding indications such as gene therapies, pain management, and kidney disease treatments. Recent minor adjustments to near-term earnings estimates and ongoing considerations around launch support costs for newly commercialized products have led institutional market participants to adopt a more cautious stance ahead of the company's upcoming quarterly financial report.
Technical Analysis of Vertex Pharmaceuticals Inc (VRTX)
Technically, Vertex Pharmaceuticals Inc (VRTX) shows a MACD (12,26,9) value of -2.043, indicating a sell signal. The RSI at 39.734 suggests neutral condition and the Williams %R at 82.722 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Vertex Pharmaceuticals Inc (VRTX)
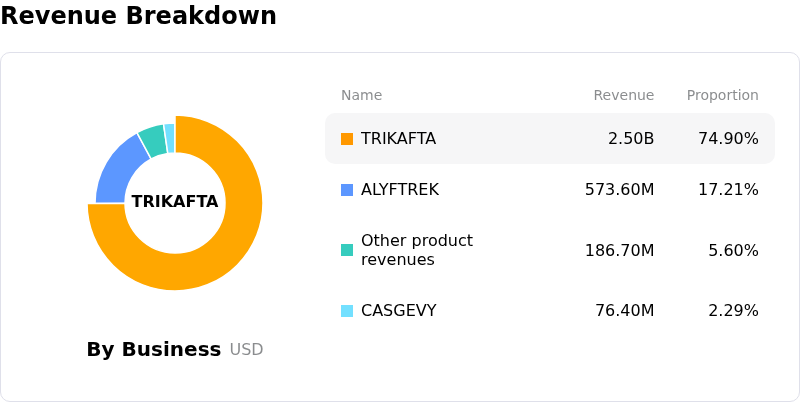
Vertex Pharmaceuticals Inc (VRTX) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $12.00B, ranking 21 in the industry. The net profit is $3.95B, ranking 16 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $571.93, a high of $672.00, and a low of $350.00.
More details about Vertex Pharmaceuticals Inc (VRTX)
Company Specific Risks:
- Cystic Fibrosis Market Saturation and Premium Valuation Sensitivity: Vertex's core Cystic Fibrosis (CF) franchise faces an increasingly saturated addressable market, having reached nearly 75% market penetration across primary target geographies. With the stock trading at a forward P/E ratio of approximately 27x to 28x and a price-to-sales ratio near 11x—representing a substantial premium over the broader biomedical sector average—any top-line growth deceleration in CF revenues leaves shares highly vulnerable to valuation compression.
- Commercial Adoption and Execution Hurdles in Non-CF Launches: The commercial rollout of non-CF assets, including the gene-editing therapy Casgevy and the acute pain drug Journavx, faces logistical complexities, high treatment costs, and payer reimbursement hurdles. Because management relies on these products to contribute over $500 million in non-CF revenues to meet full-year revenue targets, slower-than-anticipated payer coverage or patient adoption poses execution risks for top-line expansion.
- Intense Competition and Regulatory Risk in Renal Expansion: Vertex's expansion into renal indications via its $4.9 billion Alpine Immune Sciences acquisition faces fierce competitive dynamics ahead of the upcoming FDA PDUFA decision for povetacicept in IgA Nephropathy (IgAN). The presence of multiple established therapies in the IgAN market increases downside risk if regulatory approvals are delayed or if clinical trial data fail to demonstrate definitive superiority.
- Rising Operating Expenses and Downward EPS Revisions: Analyst consensus estimates for upcoming quarterly earnings have experienced downward revisions, driven by elevated operational spending as full-year 2026 combined R&D and SG&A expenses are projected between $6.3 billion and $6.45 billion. Heavy capital commitments toward recent multi-billion-dollar acquisitions, including the $10 billion purchase of Crinetics Pharmaceuticals, continue to heighten integration costs and pressure operating margins.
Find out more